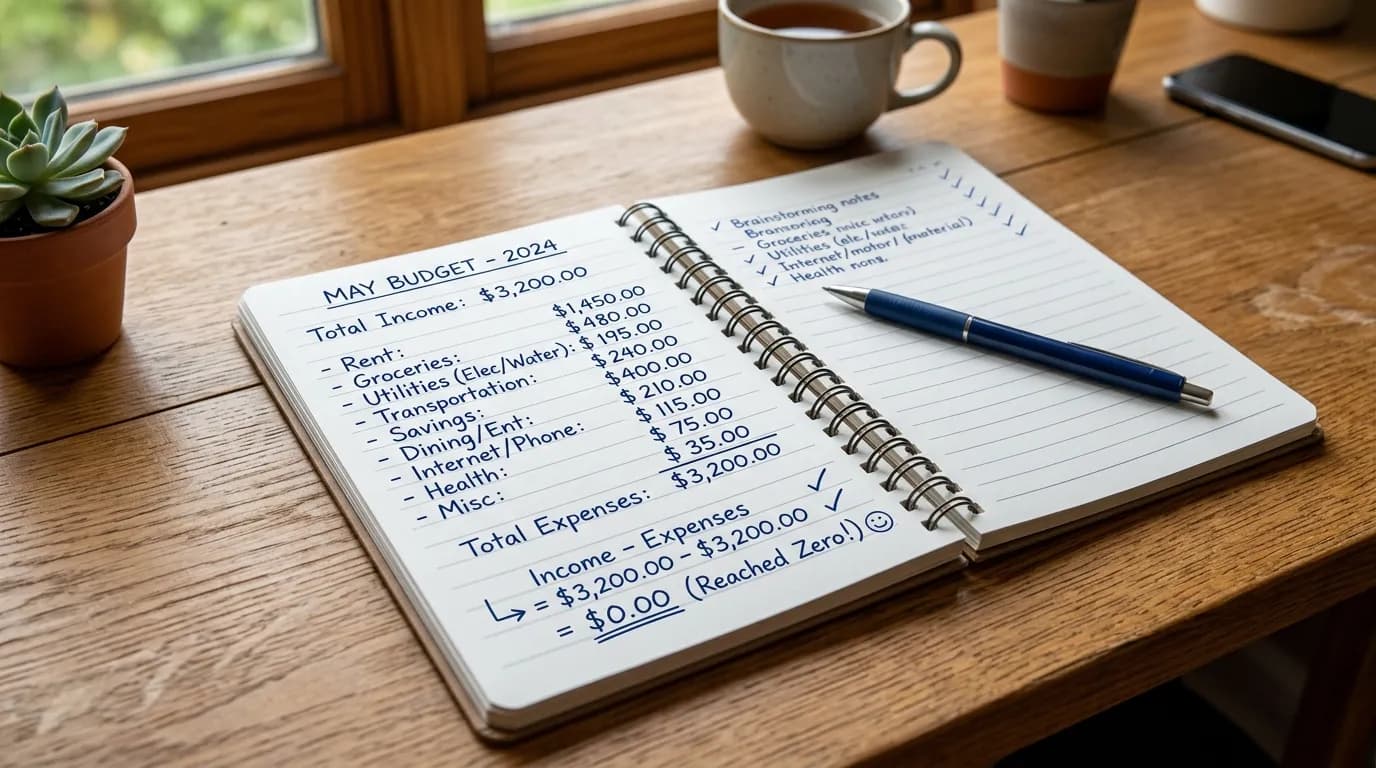
Zero-based budgeting means your planned income minus your planned assignments equals zero. Every dollar gets a job before the month gets chaotic: rent, groceries, bus fare, debt minimums, savings, haircuts, gifts, and even “fun with no guilt.” The zero is not about living with nothing left to enjoy. It is about having nothing left unassigned. This guide is educational money basics for All U Want readers—not personalized financial advice—with illustrative numbers so the method feels concrete.
If percentage rules like 50/30/20 gave you a first altitude view, zero-based budgeting is the street-level map. You can learn the bigger picture in budgeting for beginners: 50/30/20, then return here when you are ready to name each dollar. Many people use both: percentages as a health check, zero-based lines as the monthly operating plan.
First-timers often fear that zero-based budgeting will feel strict or time-consuming. Done simply, it is a monthly assignment meeting with yourself that can take under an hour once you know your numbers. The payoff is fewer mysteries. When money feels slippery, it is usually because dollars arrived without instructions. This method writes the instructions in advance.
What “every dollar a job” really means
A job can be boring or delightful. “Electric bill” is a job. “Emergency fund transfer” is a job. “Saturday coffee with a friend” is a job. “Buffer for weird pharmacy runs” is a job. Unassigned cash tends to accept the loudest job of the week—usually an impulse. Assigned cash can still be spent on fun; it is simply pre-approved fun.
Income minus assignments equals zero on paper. In real life, transactions will not match the plan perfectly. That is expected. You will move money between jobs mid-month. The skill is intentional reassignment, not psychic forecasting. Think of the plan as a first draft of your month’s priorities.
Illustration: Sam expects $3,100 take-home. After assigning rent, utilities, food, transport, minimums, savings, and planned wants, the leftover is $140. Sam does not leave $140 floating. Sam gives it a job: $80 to a vacation sinking line and $60 to buffer. Now the plan zeros out. If buffer is unused, next month those dollars can be reassigned. Nothing “vanished.”
1. Start from this month’s income only
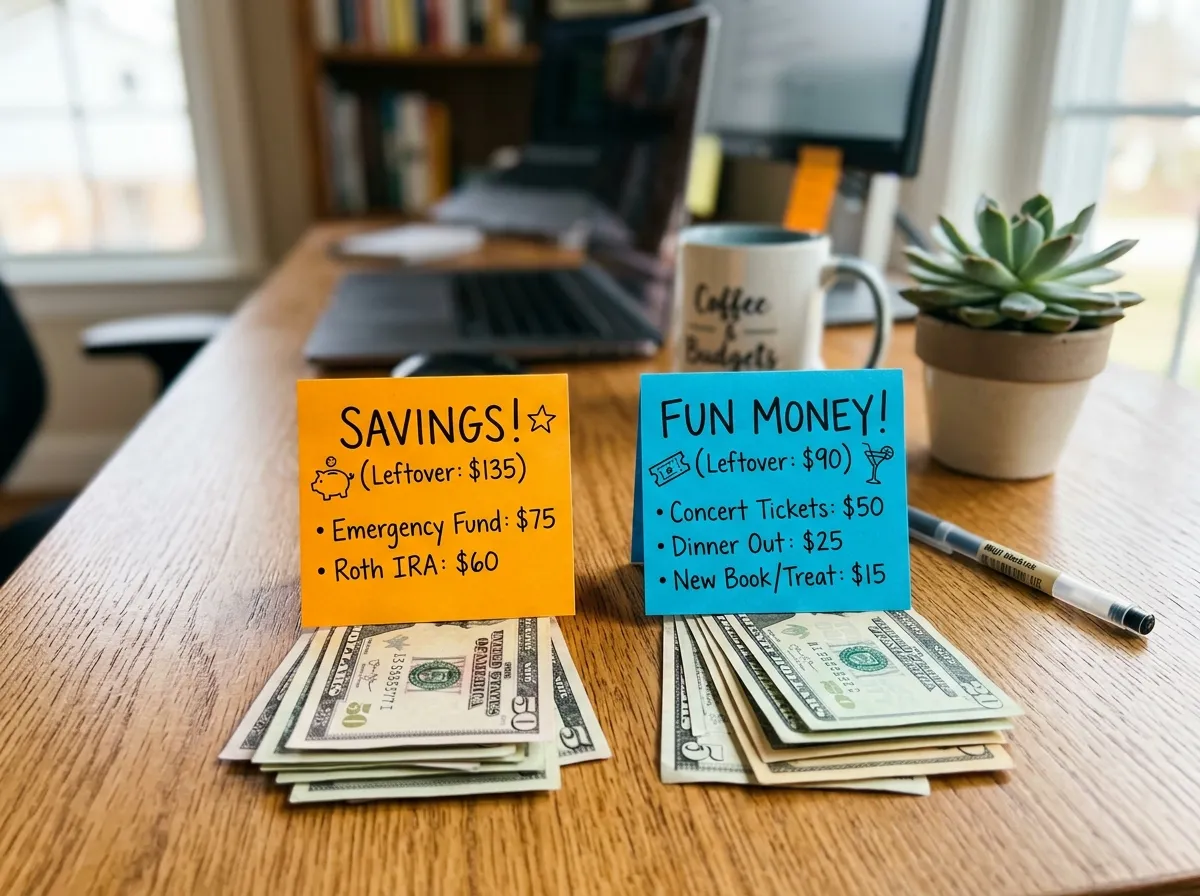
Budget the money you can reasonably expect to control this month. Do not budget a bonus you might get, a side gig you have not booked, or next month’s raise. Hope is not a category. If income is variable, use a conservative floor and create a written rule for surplus so extra dollars still get jobs when they appear.
List income sources separately if that helps: paycheck A, paycheck B, reliable side income. Sum them into one planning number. If you are paid on the 1st and 15th, you can still make one monthly zero-based plan, then pace spending between deposits. Some beginners prefer two semi-monthly zero-based plans. Choose the cadence that matches how cash actually arrives.
Illustration: Priya’s floor is $2,400. In a stronger month she receives $2,900. Her plan is built on $2,400. Her surplus rule says the first $200 of extra goes to emergency savings, the next $150 to debt, and any rest to a “skills course” fund. When $500 extra appears, jobs are already waiting. That is zero-based thinking applied to uncertainty.
Include only net deposits. Money withheld for taxes or benefits before you see it is not available to assign—unless you are self-employed and must assign dollars to a tax withholding job yourself. In that case, “tax reserve” becomes one of the most important jobs on the page.
2. Fund must-pays first
Before lifestyle categories, assign dollars to housing, basic utilities, essential groceries, required transport, insurance due this month, childcare that enables work, and minimum debt payments. These jobs protect stability. If you run out of dollars before these jobs are funded, the plan is sending a clear signal: income and obligations are misaligned for this month, and flexible categories cannot be fantasy numbers.
Write due dates beside must-pays. Zero-based budgeting is about jobs and timing. A plan that funds everything “sometime this month” can still bounce a payment on the 5th. If early-month bills are heavy, assign more of the first paycheck to those jobs and keep early flexible spending lean.
Illustration: Jordan’s must-pays are rent $1,350, utilities $170, groceries $320, transit $95, phone $40, insurance $85, debt minimums $160—total $2,220 on a $2,800 income month. That leaves $580 for savings jobs and wants jobs. Seeing $580 as the true flexible-and-future pool prevents pretending there was $1,000 of free choice.
Groceries can be a must-pay with a realistic cap. If you chronically overspend food, keep the need funded and create a separate “convenience food / delivery” want job with a smaller number. That split teaches without requiring culinary perfection.
3. Assign leftovers on purpose
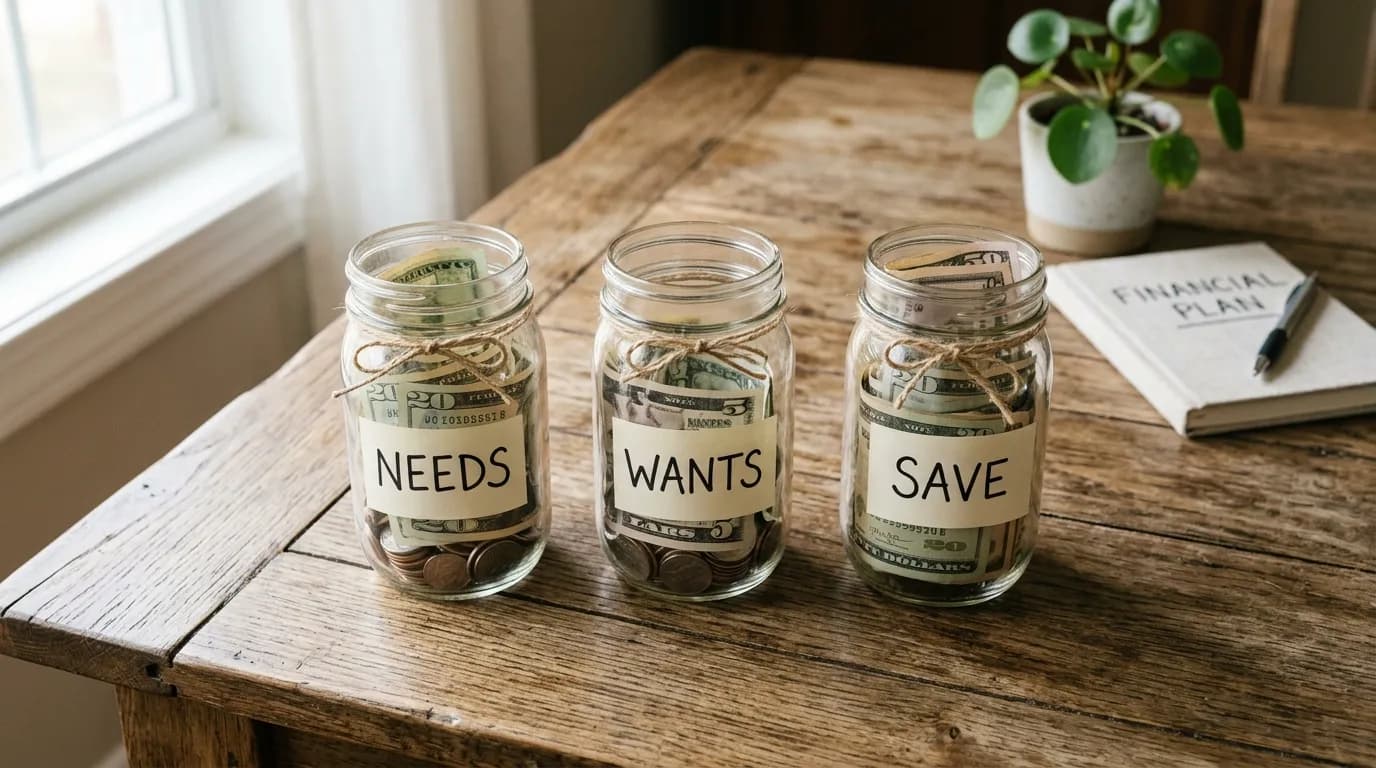
After must-pays, give every remaining dollar a named role. Typical jobs: emergency savings, extra debt payment, sinking funds for known future costs, personal spending, dining out, hobbies, gifts, and buffer. If you care about progress, fund at least one future-facing job before you fully fund all wants. If you care about sustainability, keep a small fun job even in tight months so the plan does not feel like punishment.
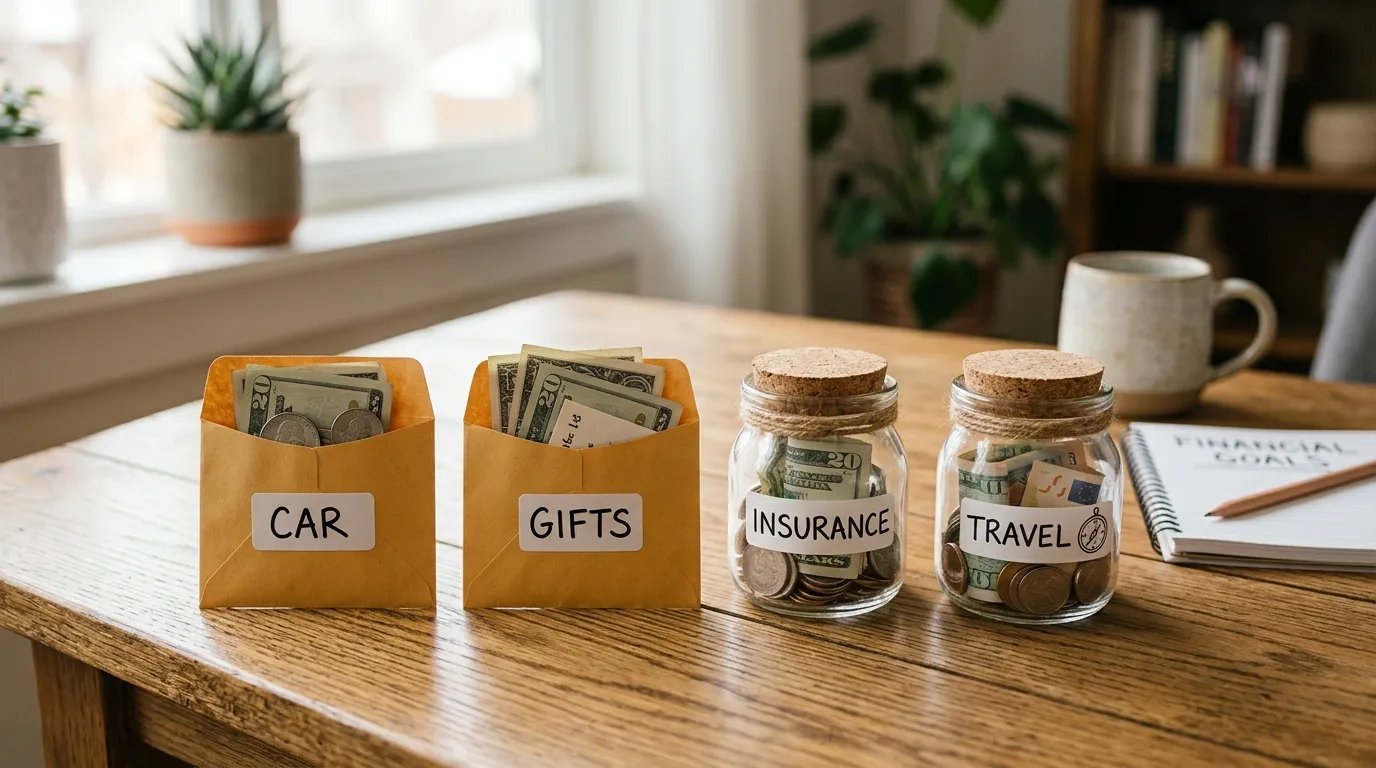
This is where sinking funds shine. A sinking fund is a job that collects money for an expected expense—car maintenance, holiday travel, annual insurance, new glasses. Instead of being shocked in November, you assign $40–$100 a month (illustrative ranges only) to that job. For a deeper walkthrough, see sinking funds explained. Zero-based budgeting and sinking funds are natural partners: one assigns every dollar now; the other makes future dollars less dramatic.
Illustration: After must-pays, Avery has $700 left on a $3,400 month. Assignments: $200 emergency fund, $150 extra card payment, $100 “car repair sink,” $80 dining, $70 personal, $50 hobbies, $50 buffer. Total $700. Income minus all jobs equals zero. Mid-month, if dining needs $30 more, Avery moves $30 from hobbies or buffer. The zero is restored by reassignment, not by pretending the overspend did not happen.
If you under-assign wants and over-assign savings in a way you will not survive emotionally, the plan will fail. Honesty is part of the method. A kept $50 fun job beats an abandoned $300 savings job that lasts nine days.
4. Rebuild monthly because life changes
Zero-based budgeting is rewritten often. New month, new plan. Some jobs roll forward with leftover balances—especially sinking funds and savings. Other jobs reset. The point is not to copy last month blindly. The point is to look at this month’s income, this month’s bills, and this month’s priorities, then assign again.
Keep a short list of repeating jobs so rebuilding is fast: the must-pays, the usual flexible categories, and two or three goal jobs. After the first month, many people finish a rebuild in thirty to forty-five minutes. The first month takes longer because you are inventing the category list.
Illustration of a change month: Casey usually assigns $120 to dining. This month includes a friend’s wedding and a work trip with unpredictable meals. Casey raises dining to $200, temporarily lowers hobby and clothing jobs, and keeps savings jobs intact. The plan still zeros out. Flexibility lives inside the structure.
At month end, glance at which jobs were chronically short or chronically padded. Adjust next month’s assignments. That review is how zero-based budgeting becomes calibrated to your real life instead of a downloaded template.
A first-timer’s first plan: step-by-step with numbers
Imagine Morgan, take-home $3,000. Step one: write $3,000 at the top. Step two: must-pays—rent $1,100, utilities $140, groceries $300, transport $120, phone $45, minimums $130—total $1,835. Remaining: $1,165. Step three: future jobs—$250 emergency fund, $200 extra debt, $100 annual car registration sink, $75 holiday sink—total $625. Remaining: $540. Step four: lifestyle jobs—$180 dining, $100 personal, $80 household extras, $60 subscriptions beyond basics already counted, $70 hobbies, $50 gifts—total $540. Remaining: $0. Plan complete.
During the month, Morgan tracks against jobs, not against a vague “be good with money” feeling. If household extras run over by $25, Morgan pulls $25 from hobbies. If a medical copay appears, Morgan uses buffer first, then trims dining. The emotional tone stays practical: move dollars, do not spiral.
If Morgan’s income next month is $2,700 because hours dropped, the rebuild starts again. Maybe extra debt shrinks, dining shrinks, and emergency fund contribution pauses for one month while the must-pays stay funded. That is not failure. That is the method working under new inputs.
Tools that keep first-timers from drowning in complexity
You can zero-base on paper, in a notes app, or in a spreadsheet with a simple sum. Fancy software is optional. What matters is a visible list of jobs, planned amounts, spent amounts, and available amounts. If a tool makes you hide from your plan, switch tools. The philosophy is portable.
Start with fewer than fifteen jobs. Merge micro-categories. “Personal care + pharmacy + random drugstore” can be one job at the beginning. Split later only if a merged job stays confusing. Complexity is earned by need, not by aesthetics.
Cash users can put physical cash into envelopes named as jobs. Card users can keep a running note or spreadsheet and adjust digitally. Hybrid users might cash out grocery and fun jobs while paying rent digitally. Pick the friction level you will maintain.
Common first-timer mistakes
Budgeting money you do not have yet. Creating forty categories on day one. Forgetting irregular annual expenses. Treating the plan as shame instead of steering. Refusing to reassign mid-month and then declaring the method “doesn’t work.” Leaving a large “misc” job that is really an unassigned pile with a costume.
Another mistake is funding only obligations and savings while assigning $0 to joy for months. That can work briefly in a crisis sprint; as a lifestyle it often backfires. Put a small joy job in the plan on purpose. Sustainability is a financial skill.
Comparing your job list to someone with a different rent, family size, or city will scramble your brain. Use other people’s lists for idea generation, not as a scorecard. Your zero is personal.
How zero-based budgeting interacts with debt and savings
Minimum payments are usually must-pays. Extra payments are separate jobs you choose after stability jobs are funded. Emergency savings often deserves an early job even at a modest amount—illustrative starter transfers might be $25, $50, or $100 per payday depending on cash flow—because surprises otherwise smash the plan. High-interest debt extra payments can share space with savings jobs based on your risk tolerance and interest rates; education here means seeing the tradeoff clearly, not prescribing one universal order for every household.
When a true emergency hits, you spend from the emergency job, then rebuild that job in later months. That cycle is normal. Zero-based budgeting makes the refill visible: a line item returns until the job is funded again.
Weekly maintenance without rebuilding everything
Once a week, spend ten to fifteen minutes checking job balances. Reassign if needed. Confirm upcoming must-pays are covered. You should not need a full rebuild every Sunday—only a steering session. Full rebuilds belong at month boundaries or after big income changes.
If you share finances, hold a short money meeting with the same agenda: income changes, must-pays, job overruns, next week’s risks. Keep it timed. Zero-based budgeting should reduce fights by replacing guesswork with a shared list of jobs.
Quick tip
Keep a small buffer job every month—even $40 or $75 in an illustration—for the annoying surprises that are not true emergencies. Buffer protects your savings jobs from death by a thousand paper cuts and makes mid-month reassignment less stressful.
When to soften the method
If you are in a chaotic season—new job, move, health flare—use a lighter zero-based plan with fewer jobs and a larger buffer. The method should serve your nervous system, not bully it. A coarse plan you update beats an elegant plan you avoid. Return to finer categories when life settles.
If debt collectors, legal issues, or unsafe money dynamics are involved, treat this as a clarity layer and seek appropriate professional or local support. A spreadsheet cannot carry what a specialist or advocate is for.
FAQ
Does zero-based mean my bank account should hit exactly $0? No. It means on your plan, every dollar of that month’s income has a job. Your account can hold money assigned to future jobs.
What if I overspend a category? Move dollars from another job. Update the plan. Learn for next month. Do not discard the whole system.
How is this different from 50/30/20? 50/30/20 sets broad percentage targets. Zero-based assigns specific jobs until nothing is unassigned. Many people use percentages as a checkup and zero-based lines as the monthly plan.
Can I do this with irregular income? Yes—plan on a floor, pre-assign surplus rules, and rebuild when deposits change.
How long until it feels natural? Often two or three monthly cycles. The first month is the slowest.
Do sinking funds break the “zero” idea? No. Money in a sinking fund already has a job. It is assigned, not leftover.
Is this financial advice? No. It is educational content to help you practice intentional money assignment. Complex situations deserve personalized professional guidance.
Related: 50/30/20 Explained · Sinking Funds Explained