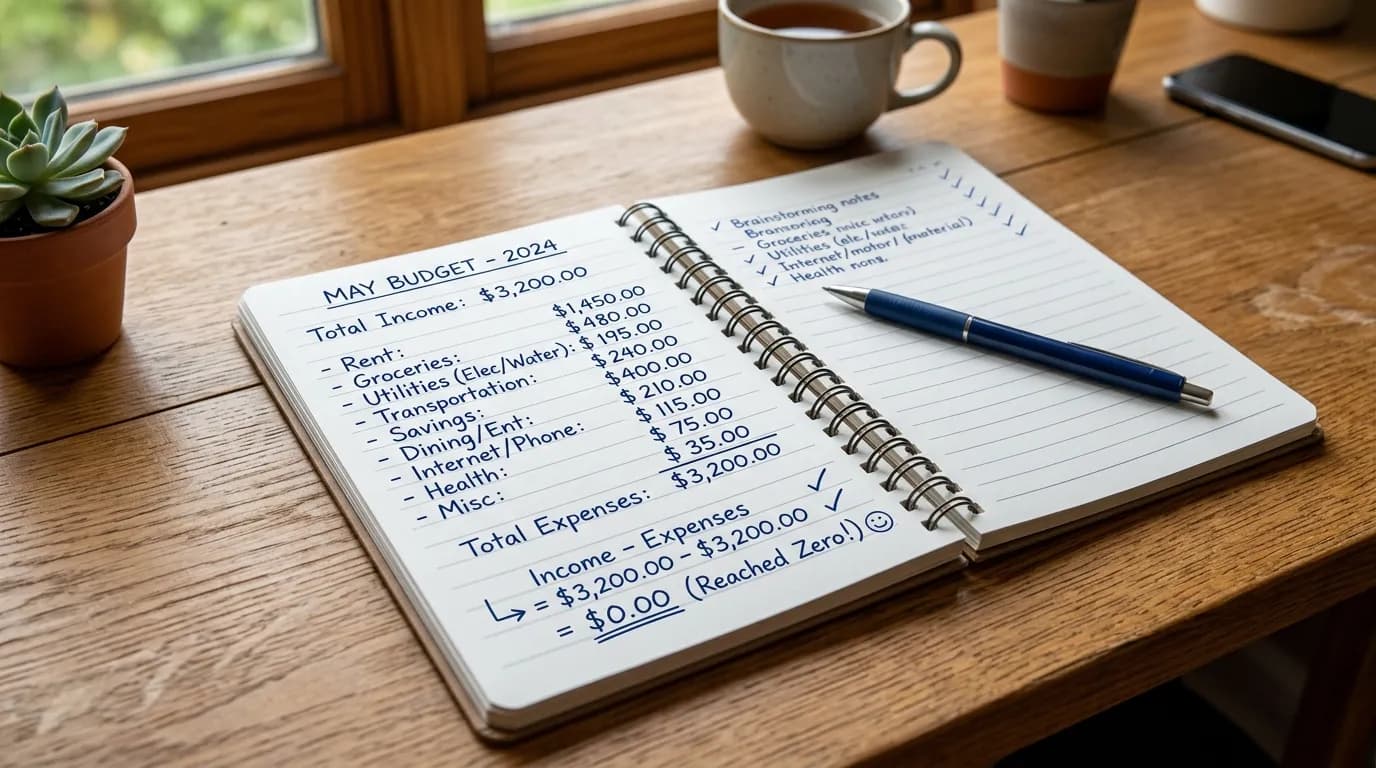
A money date is a short weekly ritual to face numbers without dread. It is not a budget overhaul, not a shame spiral, and not a three-hour spreadsheet séance. It is fifteen intentional minutes to see balances, preview bills, catch surprises, and choose one tiny fix. All U Want treats the money date as core money basics: small, repeating attention beats rare heroic catch-ups.
If you have ever avoided logging into banking apps because you feared the vibe, this ritual is for you. Avoidance grows in the dark. A money date turns on a dimmable light—enough to steer, not so bright that you freeze.
What a money date is (and is not)
A money date is a standing appointment with your financial reality. Solo or with a partner, you open the same short agenda every week. You leave with clarity and one action, not with seventeen new categories and a personality verdict.
It is not the time to redesign your entire life plan. It is not the time to argue about every coffee. Deep planning sessions can exist monthly. Weekly is for navigation: Are we solvent for the next seven days? Did anything weird hit the feed? What one move improves next week?
Fifteen minutes is a feature. Time boxes prevent rumination. When the timer ends, you stop—even if perfectionists want another pass. Consistency outranks completeness.
Think of it like brushing your teeth. Skipping for a month creates a painful catch-up dental visit. A short daily—or here, weekly—habit prevents drama.
1. Pick a recurring slot
Same day each week after a calm meal works well. Hunger, exhaustion, and late-night anxiety make numbers feel louder than they are. Choose a slot you already protect: Sunday late afternoon, Wednesday after dinner, Friday lunch if your weeks are stable. Put it on the calendar with an alert. Treat it like a class you attend.
If you share finances, pick a time both people can be halfway pleasant. A money date when one person is rushing out the door becomes a fight wearing glasses. If schedules conflict, try a shared note updated asynchronously plus a ten-minute sync call—but prefer sitting together when stakes are shared.
Protect the slot from “quick errands.” The errands expand; the date disappears. Headphones, phone on do not disturb (except banking codes), and a glass of water beat a chaotic couch scroll that never becomes a real check-in.
Name it something you will not dread. “Money date” works for many people because it sounds human. “Weekly solvency check” works for others. The label should invite attendance, not sound like court.
If you miss a week, do not double-punish with a sixty-minute makeup session. Do the normal fifteen minutes as soon as you can, then resume the schedule. Shame spirals are how rituals die.
2. Check balances and upcoming bills
Know what is due in the next seven days. Open checking, savings, and credit card balances. Glance at cash available versus bills that will clear before next payday or next money date. If rent, utilities, childcare, or minimum debt payments land this week, confirm the money will be there on the right day—or move it now.
A simple question guides this step: “Can I cover everything due in the next seven days without hoping?” Hope is not a transfer. If the answer is no, the tiny fix later in the date might be delaying a nonessential purchase, moving money from a sinking fund, picking up a shift, or negotiating a due date. Early visibility creates options. Day-of-due panic does not.
List due dates in a notes app or calendar. Many people only track rent and forget the random mid-month insurance pull. Your money date is where those land mines appear on the map.
For irregular income, check whether this week’s expected deposits are realistic. Plan from money that has arrived, not from invoices you feel optimistic about.
Partners should both see the same numbers. Hidden accounts destroy money dates. If privacy needs exist for personal fun money, define that boundary explicitly so “hidden” does not mean “secret debt.”
3. Scan for surprise charges
Catch fraud and subscription creep early. Scroll recent transactions quickly. You are not categorizing every snack. You are looking for names you do not recognize, duplicates, trials that converted, and amounts that look wrong. Circle anything suspicious and verify inside the merchant app or bank chat after the date if needed.
Surprises include: annual subscriptions you forgot, children buying in-game items, recurring free trials, double tips, hold charges that should have dropped, and charity monthly gifts you meant to pause. Surprises also include your own stress spending clusters—five delivery orders in three days—which are data for the tiny fix, not fuel for insults.
If you track spending more carefully, the money date can use your tracker’s uncategorized list as the scan surface. If you do not track yet, raw bank feeds still work. The weekly scan is often how people notice they need a lighter tracking habit in the first place.
Keep a running “what is this charge?” note. Resolve last week’s mysteries before they go stale. Merchants and banks are easier to deal with while memories and temporary authorizations are fresh.
4. Choose one tiny fix
Move twenty dollars to savings or cancel one unused app. One fix. Not twelve. The money date succeeds when it produces a small improvement that compounds: raising an automation by a percent, scheduling a bill payment, disputing a charge, setting a calendar reminder for a trial end, transferring fun money leftover to a buffer, or sending an extra payment toward high-interest debt.
Tiny matters. Overambitious fixes turn into homework you skip next week. The ritual should end with a feeling of “we handled it,” not “we opened a portal.”
Write the fix down in one line. If it needs more than fifteen additional minutes, schedule those minutes—do not silently expand tonight’s date into an hour and then resent the habit.
Rotate fix types over the month so you do not only ever cancel apps while ignoring savings, or only ever move money while ignoring a billing error. A light rotation keeps the system healthy: week of buffer, week of bills, week of subscriptions, week of debt or goals.
A fifteen-minute agenda you can copy
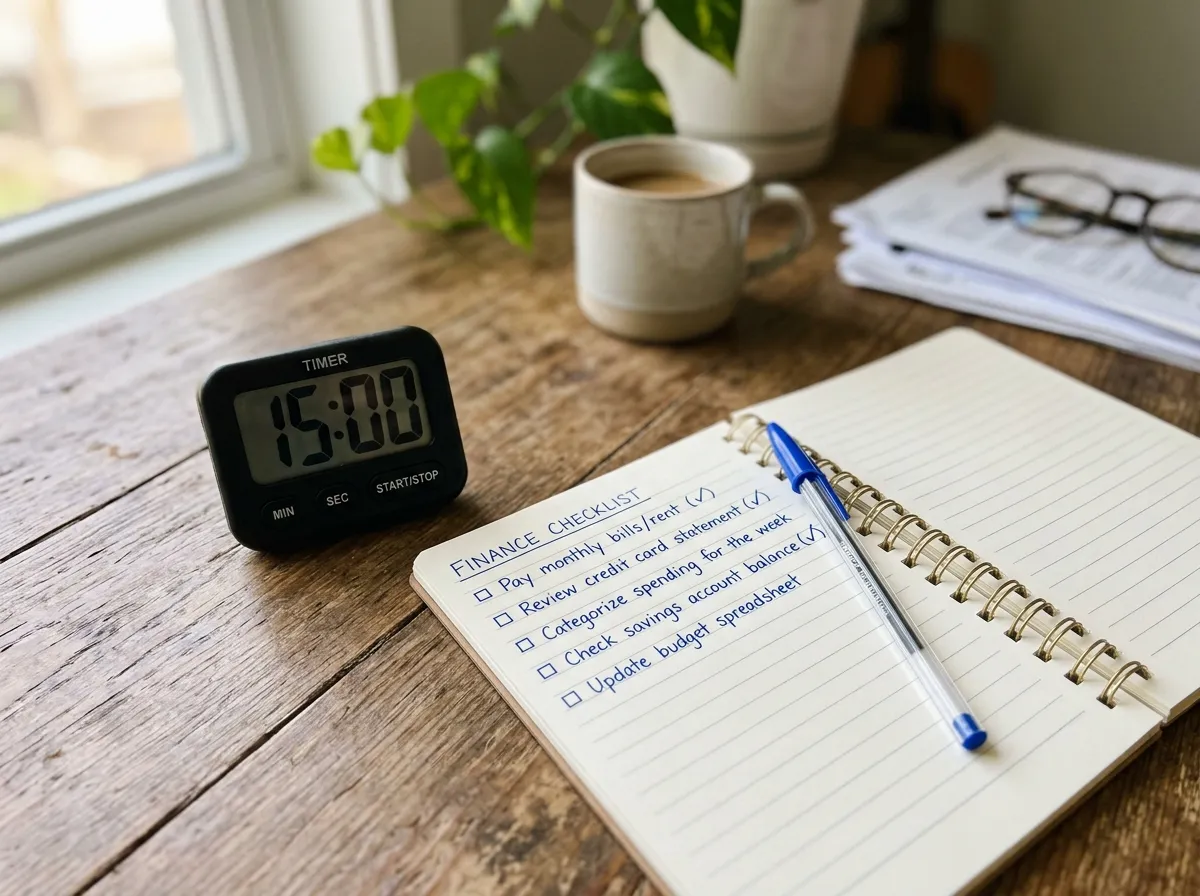
Minutes 0–2: open apps, start timer, breathe. Minutes 2–6: balances and seven-day bills. Minutes 6–11: transaction scan for surprises. Minutes 11–14: choose and start the tiny fix. Minute 15: stop, note next week’s slot, close the laptop. If you finish early, do not go hunting for problems to feel productive. Stop early and enjoy the win.
Optional opener for couples: one appreciative sentence about money teamwork before numbers. Optional closer: one sentence about a non-money plan for the week so the date does not become the whole relationship vibe.
Keep tools minimal. Bookmark your bank, card, and calendar. A single notes template with headings—Balances, Bills (7 days), Surprises, One Fix—prevents reinventing the ritual.
Solo money dates vs partner money dates
Solo dates build self-trust. You prove you can look at numbers without collapsing. Play neutral music if silence feels heavy. Sit at a table, not in bed, if bed is where anxiety loops live.
Partner dates build shared reality. Use “we” language for shared goals and “I” language for personal fun money. Avoid courtroom energy. If a topic needs a longer talk—career change, big purchase, debt strategy—park it on a monthly planning session instead of hijacking the weekly fifteen.
If one partner handles day-to-day money, the other should still attend enough dates to stay literate. Sudden sole-pilot setups break during illness, travel, or breakup. Literacy is kindness.
Roommates can run a lighter version focused only on shared bills and shared grocery funds. Call it a house dues check if “money date” feels too couple-coded.
Emotions that show up—and how to handle them
Anxiety: shorten the agenda to balances and bills only for two weeks. Competence first, optimization later. Avoidance: reduce friction—save passwords in a manager, keep the template open, set the timer for ten minutes to start. Shame: ban insults during the date. You may describe a behavior (“delivery spiked”) without describing a person (“I am trash”). Anger: pause the date, take a walk, resume tomorrow rather than weaponizing numbers.
Excitement after a good week is useful. Capture it by raising automation while mood is high. Excitement after a windfall is dangerous—still do the scan for bills before celebrating.
If money trauma is deep, a money date is still useful, but pair it with professional support when needed. A fifteen-minute ritual is not therapy; it is maintenance.
How this fits with tracking and weekly review
Spending tracking answers where money went. The money date answers whether you are safe this week and what one fix comes next. A broader weekly review might include tasks, calendar, and goals beyond money. Keep them adjacent if you want, but do not let a giant life review devour the finance check-in. Finance needs its own guaranteed slice.
If you already track daily, the money date becomes a summary and exception handler. If you do not track daily, the money date’s transaction scan is your minimum viable visibility. Either path works as money basics; perfection is optional.
Tools that help without taking over
Bank apps, calendar alerts, a notes template, and optional shareable spreadsheets are enough. Fancy dashboards help only if they reduce time-to-clarity. If setup costs four hours and you never reopen them, they failed.
Turn on low-balance alerts and large-transaction alerts so the money date is not your only detection system. Alerts are smoke alarms; the date is inspection day.
Kids in the household? A short age-appropriate money moment can exist separately. Do not force children to sit through adult anxiety. Model calm attention instead.
Tiny fix ideas when your mind goes blank
Transfer a small amount to savings. Cancel or pause one subscription. Set a reminder for a trial end. Pay a bill early that usually stresses you. Download a statement for records. Update a due-date calendar. Move upcoming rent into a holding sub-account. Send a minimum plus a little extra to the highest-interest debt. Dispute a wrong charge. Price-check car insurance for ten minutes next week (schedule it). Unsubscribe from a retailer email list that triggers spending. Soften next week by pre-deciding takeout nights from fun money.
Pick one. Start it. Schedule leftovers. End the date.
When fifteen minutes is not enough
Tax season, job loss, medical bills, or eviction risk need longer sessions and possibly outside help. The money date still helps as triage: what is due in seven days, what surprises appeared, what one call to make tomorrow. Expand with a separate “crisis money meeting” rather than pretending fifteen minutes can swallow everything.
Similarly, annual benefits enrollment and big travel planning deserve dedicated appointments. Do not cram them into the weekly ritual or you will start skipping the ritual.
Quick tip
Keep it to fifteen minutes on purpose. A short date you repeat for a year beats a perfect agenda you run twice. Timer, template, one fix—then go live your week with slightly cleaner numbers behind you.
Building the streak without becoming rigid
Track attendance loosely: a checkmark on the calendar is enough. If you complete ten of twelve weeks, you are winning. If you miss three in a row, shrink to a ten-minute balances-only version until the habit reattaches.
Travel weeks count. Hotel Wi-Fi money dates still work. If time zones wreck your slot, pick a temporary slot rather than skipping.
Celebrate streaks with non-budget-breaking rewards: a library film night, a favorite dessert already inside the fun plan, a walk playlist. Do not “reward” financial attention with a spending binge that undoes the fix.
A month of money dates: what changes
Week one feels awkward. Week two feels shorter. Week three catches a surprise charge early. Week four shows a buffer balance that moved because tiny fixes accumulated. After two months, people often report less background dread—not because money problems vanished, but because unknowns shrank.
That dread reduction is the real product. Numbers are the mechanism. Calm attention is the outcome All U Want cares about in money basics: you become someone who looks, decides, and continues.
Start this week. Put the slot on the calendar before you finish reading. When the alarm fires, run the four steps, stop at fifteen, and trust that next week’s you will show up again.
FAQ
How long does this take? Most people can start in under an hour and refine over a week—the ritual itself stays at about fifteen minutes once the template exists. First setup may take a bit longer while you bookmark accounts.
Do I need special tools? No. Simple defaults beat complicated setups you abandon. Calendar, bank apps, and a notes checklist are enough.
What if my partner refuses? Run a solo money date for your accounts and shared obligations you control. Invite without nagging; show that the meeting is short and practical. Couples counseling or a financial therapist can help when money talks always explode.
Should I do it daily instead? Daily glances help some people; the weekly date remains useful as a structured scan and fix appointment. Do not replace weekly structure with vague “I check sometimes.”
What if numbers make me panic? Shorten the agenda, use a timer, and pair the habit with support. Looking for fifteen minutes is still safer than not looking for months.
Related: How to Track Spending · Weekly Review Checklist