Not all debt is equal. A student loan at five percent and a credit card at twenty-four percent may both show as “money you owe,” but they behave like completely different problems. High-interest balances usually deserve attack before low-interest installment loans, because interest is a fee that compounds while you sleep. All U Want’s money-basics approach is simple: keep every account current, protect a tiny cash buffer, then pour extra dollars at the debt that costs the most to carry.
This guide walks through how to sort your balances, choose an attack order that actually saves money, decide when a “psychologically easier” snowball still makes sense, and avoid the common trap where you pay off one card only to reopen the same hole next month. You do not need a spreadsheet empire. You need a clear list, a weekly habit, and a rule for where surplus cash goes.
Why interest rate changes the whole game
Debt is a claim on future income. Interest is the price of that claim. When the price is low, stretching payments can be rational if it frees cash for emergencies, career moves, or retirement matches. When the price is high, every month of delay is expensive. Credit cards, store cards, payday-style products, and some personal loans often sit in that high-cost zone. Mortgages, many federal student loans, and some auto notes sit lower.
People mix these together because the monthly statement feels the same: a due date, a minimum, a balance. Emotionally they are peers. Mathematically they are not. A five-hundred-dollar swing on a high-rate card can erase weeks of careful grocery cuts. The same swing on a low-rate installment loan barely moves the long-term cost. Attack order is how you stop treating unequal debts as equals.
All U Want frames this as a money-basics skill, not a personality test. You are not “bad with money” because you carry a mix of balances. You are unfinished at ranking them. Ranking is learnable in one sitting.
1. Sort by interest rate
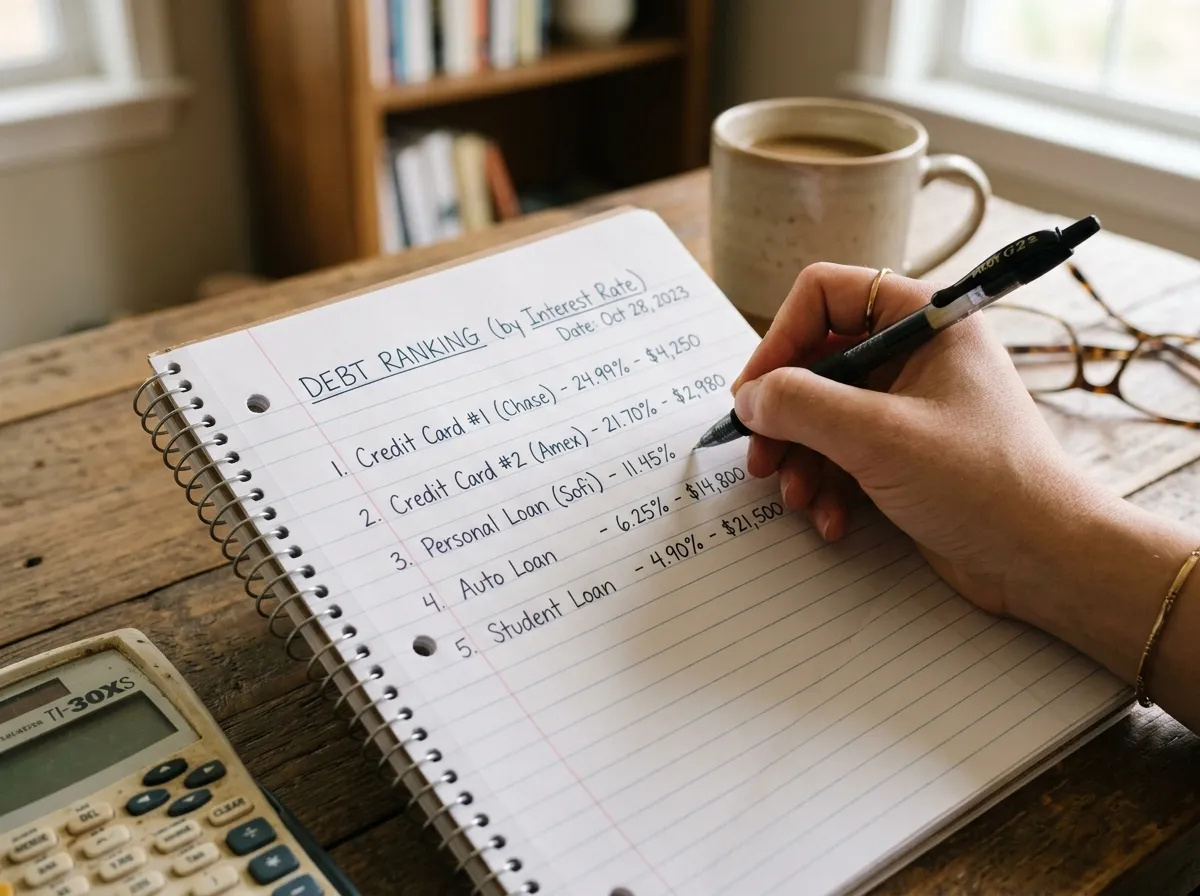
Open every statement or app and write three columns: name of debt, current balance, and annual percentage rate (APR). If you only have a monthly finance charge, convert roughly by remembering that cards advertise APR, not “this month’s fee alone.” Sort the list from highest APR to lowest. Cards and payday-style debt often sit at the top. Personal loans, auto loans, and student loans usually fall lower. A 0% promotional balance is a special case: treat the promotional end date as a timer, not a free forever pass.
Do not sort by balance size first. Large low-rate loans look scary; small high-rate cards look harmless. The cost ranking is the opposite of that instinct. A twelve-hundred-dollar store card at twenty-nine percent can outrun a twelve-thousand-dollar student loan at six percent in pure interest burn for a while. Your list should make that obvious at a glance.
If two debts have nearly identical rates, break ties with balance size or due-date pain. If one is about to leave a 0% window and jump to a high rate, promote it in the queue before the jump happens. Sorting is not a one-time museum piece. Re-sort when rates change, when you refinance, or when a promo ends.
Capture minimum payments next to each line. You need them for the next rule. Without minimums written down, people “focus” on one debt and accidentally miss another due date. Missed due dates create fees and score damage that erase the clever math of your attack plan.
2. Keep minimums current everywhere
Avoid late fees while you focus. The attack plan only works if every other account stays green. Minimum payments are the price of staying eligible to play. Automate them if you can. Set calendar reminders if you cannot. Treat “minimum day” as non-negotiable the same way rent is non-negotiable.
People skip minimums on “small” accounts because the balance feels unimportant. Lenders do not share that feeling. One late fee can equal days of surplus payment you meant to throw at the high-rate target. Collections calls also destroy the calm you need to stick with a multi-month payoff.
If cash is so tight that minimums alone strain the month, pause the heroics and rebuild breathing room first. That may mean cutting nonessential subscriptions, negotiating a temporary hardship plan, or picking up a short-term income bump. An attack order without room to pay minimums is a fantasy schedule. All U Want prefers boring solvency over dramatic payoff charts that break in week three.
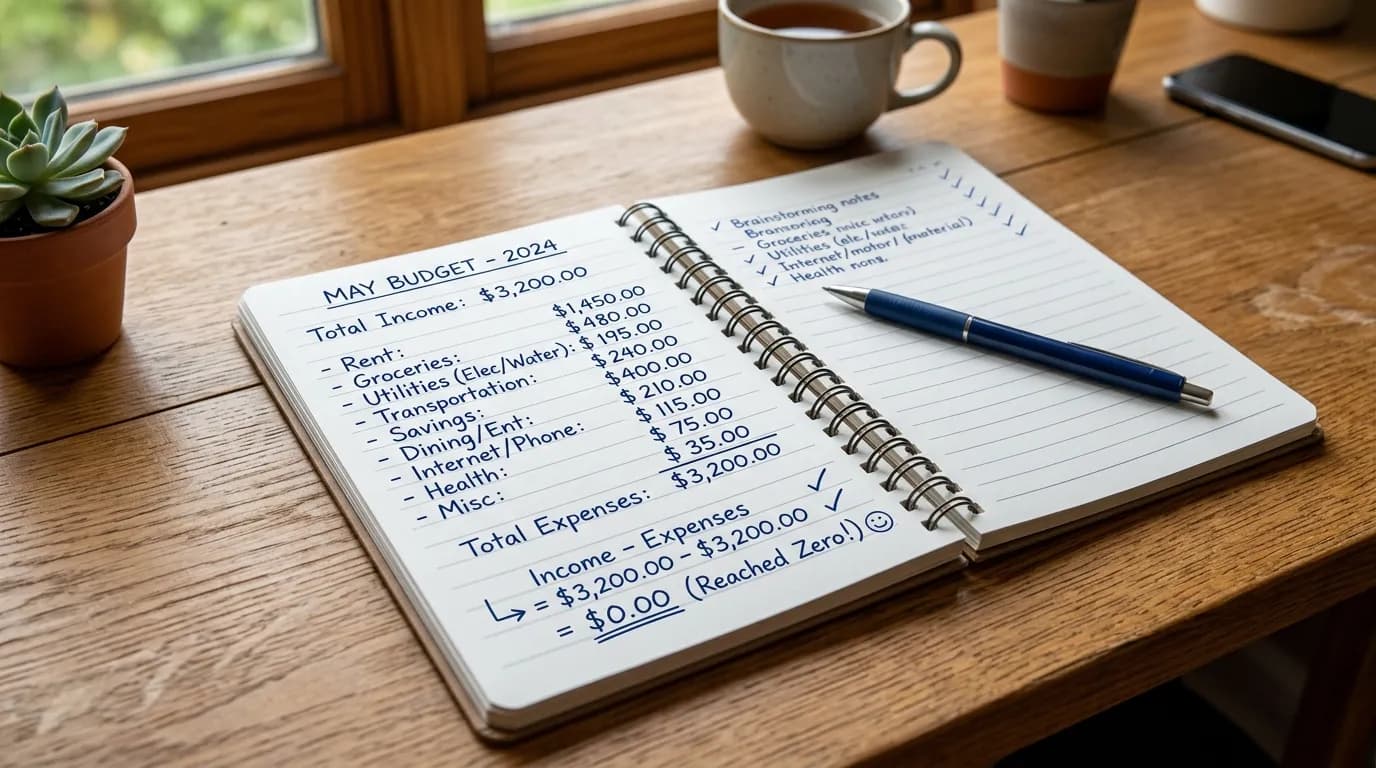
Once minimums are covered, label everything leftover as “attack dollars.” Attack dollars are not vibes. They are a number: paycheck surplus after bills, groceries, transport, and your small buffer contribution. Write that number. Even eighty dollars a month is an attack plan if it hits the right target every time.
3. Attack the costliest balance
Extra payments go where interest hurts most. That is the avalanche method in plain language. Pay minimums on all debts. Send every spare dollar to the highest APR until it hits zero. Then roll that entire payment (old minimum plus surplus) onto the next highest APR. The payment snowball grows, but the target order follows cost, not feelings.
Why this order wins on pure math: interest stops accruing on the expensive balance sooner. You free cash that would have evaporated as finance charges. Over a year, the difference between attacking the right debt and the wrong debt can equal a vacation, a new phone without financing, or several months of emergency savings.
Make the payment boring and automatic. After payday, move attack dollars the same day. Do not wait to “see what is left.” What is left is usually less. If your employer offers split direct deposit, send a slice straight toward the high-rate payment when the bank allows it. Friction is the enemy of consistent attack.
Call the lender if a large extra payment might get misapplied to future minimums instead of principal. Ask how to designate principal reduction. Keep confirmation numbers. Screenshots beat memory when a statement looks wrong two weeks later.
Track progress with one visible metric: highest-APR balance remaining. Watching that number fall is more motivating than watching total debt, because total debt includes low-rate loans that should not be your emotional weather vane this month.
4. Keep a small emergency buffer
Otherwise new debt replaces old debt. A classic failure mode is draining every dollar into payoff, then putting a car repair on the same high-rate card you just celebrated clearing. You did not fail at discipline. You failed at sequencing. A starter emergency buffer—often five hundred to one thousand dollars, or one month of bare essentials if that is reachable—belongs beside the attack plan, not after it in some distant future.
How to split when money is scarce: keep minimums current, fund the buffer in tiny automated transfers, and still send something to the high-rate target. Something beats nothing. Twenty dollars to savings and sixty to the card is better than eighty to the card and zero protection. When the buffer hits your starter goal, redirect the buffer transfers into the attack pile until the expensive debt is gone, then rebuild the buffer larger.
Park the buffer in a separate savings account you do not debit for coffee. Mentally label it “break glass.” Using it for a true emergency is success, not failure—as long as you rebuild. Using it for a sale is how buffers die quietly.
All U Want pairs this idea with longer emergency-fund work because starter cash and full funds are different seasons. Right now you need enough to stop the debt treadmill from restarting. Later you expand coverage. Sequence prevents whiplash.
Avalanche vs snowball: when feelings beat math
Avalanche (highest rate first) usually costs less interest. Snowball (smallest balance first) usually feels faster because accounts disappear sooner. If stress is blocking action, snowball can still be a valid bridge. A plan you follow beats a mathematically perfect plan you abandon after two anxious weeks.
A hybrid works well for many people: knock out one tiny balance for a quick win, then switch permanently to highest rate. Or use avalanche for everything above a rate threshold (say eighteen percent) and snowball only among near-equal mid-rate debts. Write the rule so you do not renegotiate with yourself every payday.
Shame is a bad advisor. If a partner or family member needs visible progress to stay engaged, snowball’s quick closures can be relationship glue. If you are solo and analytically wired, avalanche’s cleaner cost story may stick better. Choose the version you will still run in month seven.
What usually counts as high-interest vs low-interest
There is no universal cutoff, but practical buckets help. High-interest often means revolving credit in the mid-teens and above, especially anything north of twenty percent. Medium might be personal loans in the high single digits to mid-teens. Low often means secured or federally backed installment debt in the low-to-mid single digits—though your local rates vary with credit profile and era.
Store cards deserve special suspicion. They are marketed as “ten percent off today” and priced like a trap tomorrow. Payday and cash-advance products sit in a category of their own: treat them as emergency exits you never want to re-enter, and clear them with urgency even if the balance looks small.
Student loans and mortgages are frequently lower rate and longer term. Attacking them aggressively before clearing twenty-four-percent cards is usually a costly preference, not a virtue. Exceptions exist—for example, a variable rate spiking, or a loan with harsh default consequences—but those are special cases, not the default All U Want order.
0% intro APR offers are neither free nor forever. If you can truly pay the balance before the promo ends without starving your buffer, using the window can be smart. If you cannot, the post-promo rate may vault that balance to the top of your attack list overnight. Calendar the end date the day you open the account.
Should you refinance or consolidate?
Sometimes a lower-rate personal loan can replace several high-rate cards. That only helps if three conditions hold: the new rate is meaningfully lower after fees, you stop adding new card balances, and the payment plan is shorter or at least not stretched so long that total interest creeps back up. Consolidation without behavior change is a balance transfer costume party.
Balance transfer cards with fees need pencil math. A three-percent fee on a transfer can still beat twenty-four-percent interest if you clear the balance inside the promo window. If you only pay minimums until the promo dies, you paid a fee for the privilege of returning to high interest. Write a payoff calendar before you swipe the transfer.
Refinancing a low-rate student loan into a higher private rate to “simplify” is often a step backward. Simplification should not raise your cost of money. All U Want prefers fewer high-cost accounts, not fewer accounts at any price.
Credit scores, utilization, and payoff order
Paying high-rate revolving debt also tends to help credit utilization, which can support score recovery over time. That is a side benefit, not the primary goal of attack order. Do not delay a high-rate payoff to game a score for a purchase you do not need. Do use improved scores later for better refinance options if they appear.
Closing a card after payoff can raise utilization ratios on remaining cards. Sometimes leaving an old card open with a zero balance (and no annual fee) is fine. If the card has a nasty fee or tempts overspending, closing may still be right. Decide with eyes open, not from forum absolutism.
A one-hour setup you can finish tonight
Hour plan: fifteen minutes listing debts and APRs, ten minutes confirming minimums and due dates, ten minutes automating minimums, ten minutes scheduling the surplus transfer to the top target, fifteen minutes opening or labeling a buffer savings pocket. You will not finish the debt in an hour. You will finish the operating system that finishes the debt.
Print or screenshot the sorted list. Put the top target’s name on a sticky note near your desk or lock screen for a week. Visibility reduces renegotiation. After the first month, review whether attack dollars actually arrived. If not, shrink the fun budget or raise income before blaming “willpower.”
Couple or roommate households should agree on the attack target in writing. Mixed strategies—one person snowballing secretly while the other avalanches—create resentment and duplicate effort. Shared money-basics means shared ranking.
Weekly maintenance so the plan survives real life
Once a week, spend ten to fifteen minutes checking that minimums posted, that the surplus payment posted to the correct account, and that no new high-rate balance appeared. Surprise medical bills and “buy now, pay later” installments can sneak into the high-cost tier. Catch them early.
If income dips, protect minimums and buffer first, then temporarily shrink attack dollars without canceling the habit entirely. A five-dollar payment keeps the identity of “I attack high-interest debt” alive. Identity continuity matters more than hero months followed by ghost months.
If income rises, raise attack dollars before lifestyle. A raise that becomes a nicer subscription stack is how high-rate balances become permanent roommates.
Common myths that keep expensive debt alive
Myth: “I should invest instead of paying six-percent debt.” Sometimes true for low-rate debt when you have an emergency fund and a workplace match. Rarely true for twenty-percent cards. Guaranteed interest avoided often beats uncertain market returns, especially while you are still building basics.
Myth: “Minimum payments mean I am fine.” Minimums are designed to keep you solvent for the lender, not optimized for you. Fine is not free.
Myth: “I will attack debt after I feel ready.” Readiness follows systems. Systems do not wait for a cinematic motivation day.
Myth: “Low balance means low priority.” Low balance with high APR is often the best first avalanche target and a decent snowball target. Priority follows cost or momentum strategy—not vibes about the number of digits.
Quick tip
If stress is blocking action, snowball can still be a valid bridge. Clear one small balance for proof, then switch to highest APR so math and motivation both get a turn. Keep minimums current, guard a starter buffer, and point every leftover dollar at the costliest remaining claim on your future. That is the All U Want attack order in one sentence.
Putting it together with the rest of money basics
Debt attack order sits next to spending awareness and emergency cash. Without tracking, you cannot find attack dollars. Without a buffer, paid-off cards reopen. Without a card payoff playbook, high-rate revolving debt lingers even when you “know” it is expensive. Use this post to rank. Use your card-payoff and emergency-fund habits to execute. Ranking without execution is a tidy notebook. Execution without ranking is hard work pointed at the wrong hill.
Revisit your sorted list every time something big changes: a refinance, a new loan, a rate hike, a windfall. Windfalls should hit high-interest debt before lifestyle upgrades unless your buffer is empty. Empty buffers get first claim on surprise money; expensive interest gets second; nice-to-haves get third. That priority ladder prevents the familiar story where a bonus becomes furniture and the card balance stays put.
You do not need to hate yourself for past balances. You need a rate-sorted list, automated minimums, a small cash cushion, and a stubborn habit of sending surplus to the costliest debt. Do that long enough and the expensive accounts disappear. Then you can decide, calmly, how aggressively to handle the cheaper ones—on purpose, not by panic.
FAQ
How long does this take? Most people can build the sorted list and automations in under an hour and refine the attack dollar amount over a week of real spending. Paying off the balances themselves takes as long as the math requires; the system can start immediately.
Do I need special tools? No. Simple defaults beat complicated setups you abandon. A notes app, a sheet of paper, or your bank’s transfer tools are enough. Fancy debt apps help only if you will open them.
Should I pause investing to kill high-interest debt? Workplace matches are often worth keeping if you can still cover minimums and a tiny buffer. Beyond that, clearing very high APR balances is usually the cleaner “return.” Low-rate installment debt is a different conversation.
What if my highest rate debt is also my largest? Avalanche still applies. It may feel slow at first. Measure progress by interest avoided and balance remaining on that account, not by how many accounts you closed this month.
What if I share finances with someone who disagrees? Agree on minimums and buffer first—those are safety. Then negotiate one attack target for thirty days and review. Short experiments beat endless theoretical debates.
Related: Pay Off Credit Card Debt Faster · Emergency Fund